
Your portfolio should know what it is for.
Most are built to a model. Yours is built to your number, and to the life it has to pay for.
One planEvery area connects to the same plan, so a move in your business and a move in your personal life are never made in isolation.
A registered investment advisor and a broker are not the same job.
A brokerage relationship
"This is suitable for you."
A recommendation can be suitable and still be the more expensive of two suitable options, and the firm may be paid by whoever issued it. Suitability is a floor, not an obligation to choose the best available.
A registered investment advisor
"This is in your best interest, and here is what it costs."
A fiduciary duty that applies continuously, not just at the moment of a recommendation, and compensation that comes from you alone so there is nothing to disclose about who else is paying.
Nine planning areas, run as one plan.
The portfolio is one of the nine, and it is the one most affected by the other eight. Each links to the page that covers it properly.
Tax
Where each holding sits matters as much as what it is, so the tax work and the account it lands in are one decision.
Retirement
The income the portfolio has to produce, and how much of it can sit in something that moves.
Investments
Built to a risk score rather than a house model, rebalanced on rules, and held in your name at a third party.
Company Plans
The plan's fund lineup measured against a written investment policy, and the owner's own account coordinated with everything else.
Estate
Beneficiary designations override a will, so the account registrations get checked before anything is drafted.
Business
Usually the largest holding you own, which is why the accounts have to be arranged around it, not beside it.
Education
A 529 has a spending date, so it gets its own glide path rather than riding along with the retirement money.
Cash Flow
How much has to stay liquid, which sets the floor everything else is invested above.
Insurance
Cover the losses you could not absorb, so the portfolio is never the thing that has to be sold in a bad year.
Five steps, and the first one is free.
The EVOKE® process. Nothing moves and nothing changes until you decide it should, and I will tell you early if this is not a fit.
Exploration
A relaxed call. I listen, I do not pitch, and it costs nothing.
Vision
What the money is actually for, answered before any numbers are run.
Obstacles
What stands between the two, named honestly rather than talked around.
Knowledge
The work I go away and do: returns, statements, documents, the company.
Execution
The plan on one page, then the meetings that keep it moving.
The biggest position in your portfolio may not be in your portfolio.
For most owners in Montgomery County the business is half or more of everything they have, and it is an illiquid holding they also work at. A portfolio built without counting it is a portfolio built on the wrong denominator.
So the investments get arranged around that concentration rather than beside it: what the accounts hold, what they must not hold, and what has to be liquid on the day the company is not.
How the Portfolio Works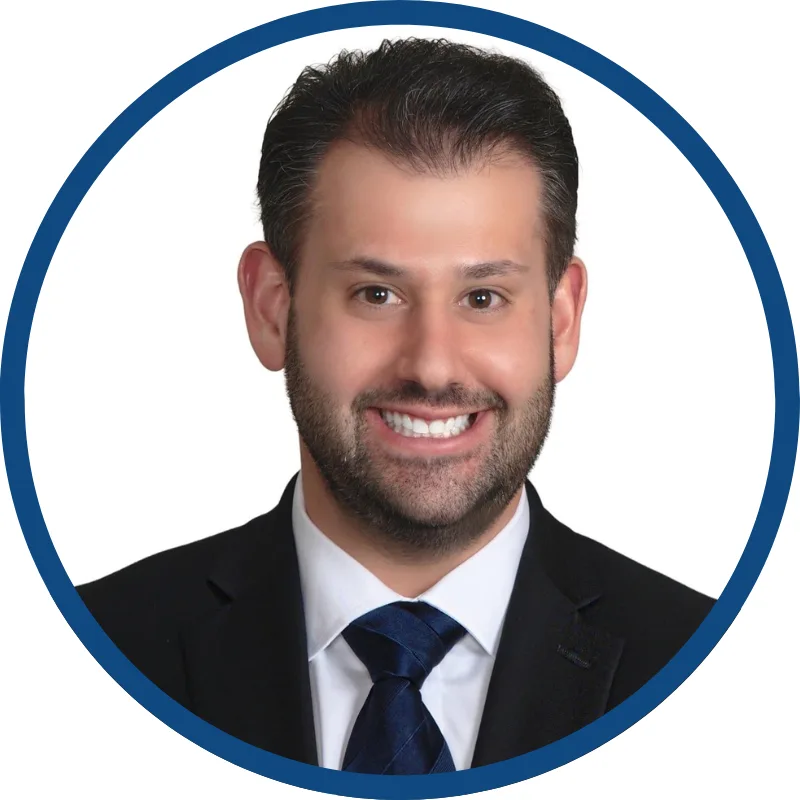
Alan Rhode, CFP®, CPWA®, CVGA®, CEPA®, RLP®
Based in Blue Bell. Managing for people anywhere.
I am in Blue Bell, in Montgomery County, and I work with households and owners across Greater Philadelphia, Chester and Bucks counties. Because custody sits with an independent platform and meetings run by Zoom or phone, where you live changes nothing about how the work is done or where your money is held.
Investing involves risk, including possible loss of principal. Nothing here is a recommendation to buy or sell any security, and no allocation shown is advice for your circumstances. Past performance does not indicate future results.
More ways I work with people here
- Financial advisor in Blue BellWho I am and how I work with people in Blue Bell
- Financial planner in Blue BellThe plan, and the process for building it
- Retirement planning in Blue BellIncome, Social Security and withdrawals
- Tax planning in Blue BellBrackets, Roth conversions and Pennsylvania rules
- Business advisory in Blue BellGrowth, value and exit planning for owners
- For entrepreneurs in Blue BellPlanning built around a business you own
Let's look at what you hold.
A free thirty minute call, by phone. No pitch and no obligation, just a conversation about what you want and whether we are a fit.
Book a Free CallKeep Reading
From the blog
The 2027 401(k) and IRA Limits: What Changed and What to Do Now
The IRS announced the 2027 retirement plan limits on November 12, 2026. The 401(k) limit rises to $25,500, the total cap to $75,000, and the IRA limit stays at $7,500. Here is every number that changed, what it means for employees and business owners, and what to do before January.
Read MoreYour Stack of Finance Apps Is a Growing Fraud Surface
Every linked finance app adds a login someone can take over, so a growing stack widens your fraud and data exposure faster than any single app improves your finances.
Read MoreThe Backdoor Roth IRA in 2026: A Step-by-Step Guide
If your 2026 income is too high for a direct Roth IRA contribution, the backdoor Roth lets you get the same $7,500 ($8,600 at age 50 or older) into a Roth. Here is how to do it step by step, how to report it, and the mistakes that make it taxable.
Read More