
Financial advisor for entrepreneurs and business owners in Blue Bell.
I work with business owners whose wealth and work are the same thing. Most of what you own is tied up in a company you cannot easily sell, and no one has put the whole picture on one page. That is the job.
Not a business owner? For individuals and retirees, see my page on working with a financial advisor in Blue Bell.
A plan built for a salary does not survive your balance sheet.
What most plans assume
"Steady paycheck, a 401(k), and a retirement date."
Your income moves with the company. Your largest asset is illiquid and hard to value. Your CPA, your attorney and your advisor have never been in the same meeting, and you find out what you owe in April.
What you get here
"Here is what the company is worth, what it needs to be, and what happens if you stop."
The business and everything else run as one plan instead of three separate rooms. One page you keep, and one person who holds the whole picture.
Two halves of one plan, run together.
The company is the engine. It is not the whole life, and it should not be the whole plan.
What the company is actually worth
A baseline assessment of what it is worth, and an honest read on what caps it. Owner dependence, customer concentration and messy books all cost you at the table, and every one of them is fixable with time.
An exit shaped years ahead
The best outcomes are engineered long before a buyer appears. What the sale needs to clear to fund the rest of your life, and whether it currently will.
Pay, structure and the tax bill
Compensation and entity structure planned across the whole year rather than reacted to in April, because those decisions drive the number more than any investment pick.
The retirement plan your payroll supports
Not the one with the highest headline limit. The one that fits your staff, your cash flow and how much you actually want to put away.
Money that is not the business
Investments held outside the company so your entire life is not one concentrated bet on one buyer in one industry in one year.
Estate and insurance that match reality
Documents built around the ownership structure you actually have, and coverage sized to the personal guarantees you have already signed.
My father's practice carried our whole family.
He ran a solo dental practice. When he got sick I stepped in to keep the doors open, then led the sale so my mother would be okay. I learned what it costs when the plan for a business is made at the worst possible moment rather than years ahead, and how few advisors are built to help with it.
So I built the opposite. Modern Wealth is independent and fee-only. I earn nothing but the fee you pay me. No products, no commissions, no third party paying for the advice you get.
More About Me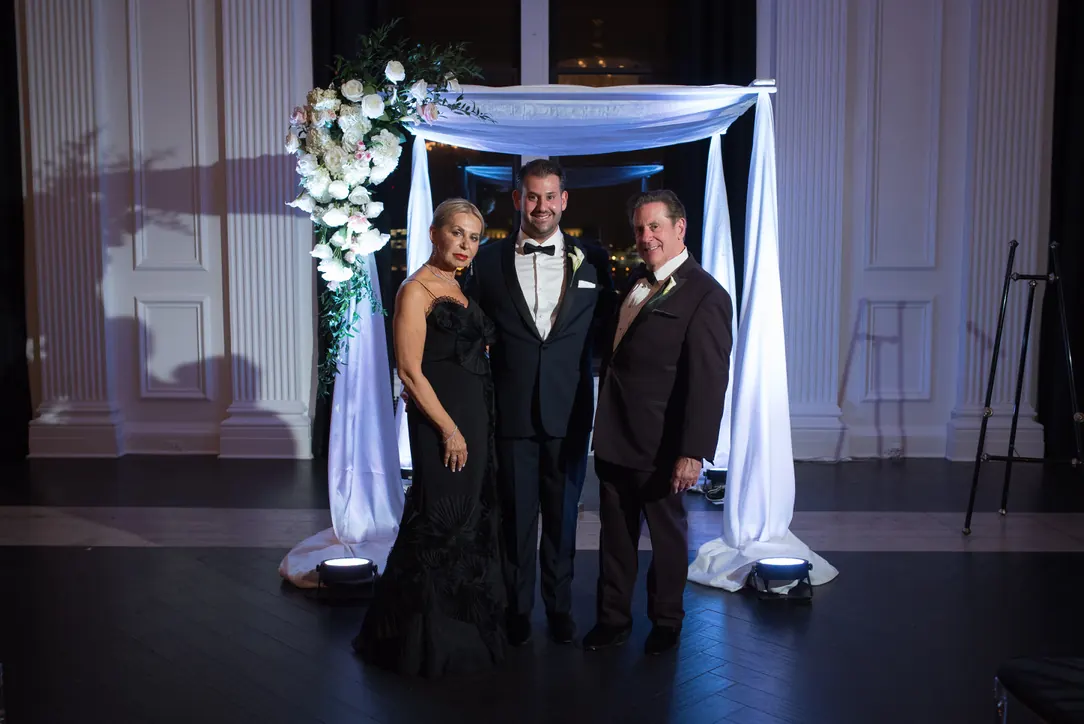
Alan with his parents, the reason this work exists
Based in Blue Bell. Working with owners anywhere.
I am a financial advisor in Blue Bell, in Montgomery County, and I work with owners throughout Greater Philadelphia, Chester and Bucks counties. Meetings happen by Zoom or phone rather than in an office, so the same work suits owners anywhere in the United States just as well, and plenty of my clients are nowhere near Pennsylvania. Being local matters when it helps: I know the CPAs, attorneys and exit planners here, and if you are one of them I collaborate around your client rather than over the top of them.
More ways I work with people here
- Financial advisor in Blue BellWho I am and how I work with people in Blue Bell
- Financial planner in Blue BellThe plan, and the process for building it
- Investment advisor in Blue BellHow portfolios are built and managed
- Retirement planning in Blue BellIncome, Social Security and withdrawals
- Tax planning in Blue BellBrackets, Roth conversions and Pennsylvania rules
- Business advisory in Blue BellGrowth, value and exit planning for owners
Let's put the whole picture on one page.
A free thirty minute Exploration Call. No pitch and no obligation, just a conversation about what you want and whether we are a fit.
Book a Free CallKeep Reading
From the blog
The 2027 401(k) and IRA Limits: What Changed and What to Do Now
The IRS announced the 2027 retirement plan limits on November 12, 2026. The 401(k) limit rises to $25,500, the total cap to $75,000, and the IRA limit stays at $7,500. Here is every number that changed, what it means for employees and business owners, and what to do before January.
Read MoreYour Stack of Finance Apps Is a Growing Fraud Surface
Every linked finance app adds a login someone can take over, so a growing stack widens your fraud and data exposure faster than any single app improves your finances.
Read MoreThe Backdoor Roth IRA in 2026: A Step-by-Step Guide
If your 2026 income is too high for a direct Roth IRA contribution, the backdoor Roth lets you get the same $7,500 ($8,600 at age 50 or older) into a Roth. Here is how to do it step by step, how to report it, and the mistakes that make it taxable.
Read More